On this page
Do You Need Earthquake Insurance? A Plain-English Guide
Discover how earthquake insurance works, what standard policies exclude, how deductibles are calculated, and whether your property needs coverage.
The Hidden Gap in Standard Homeowners Policies
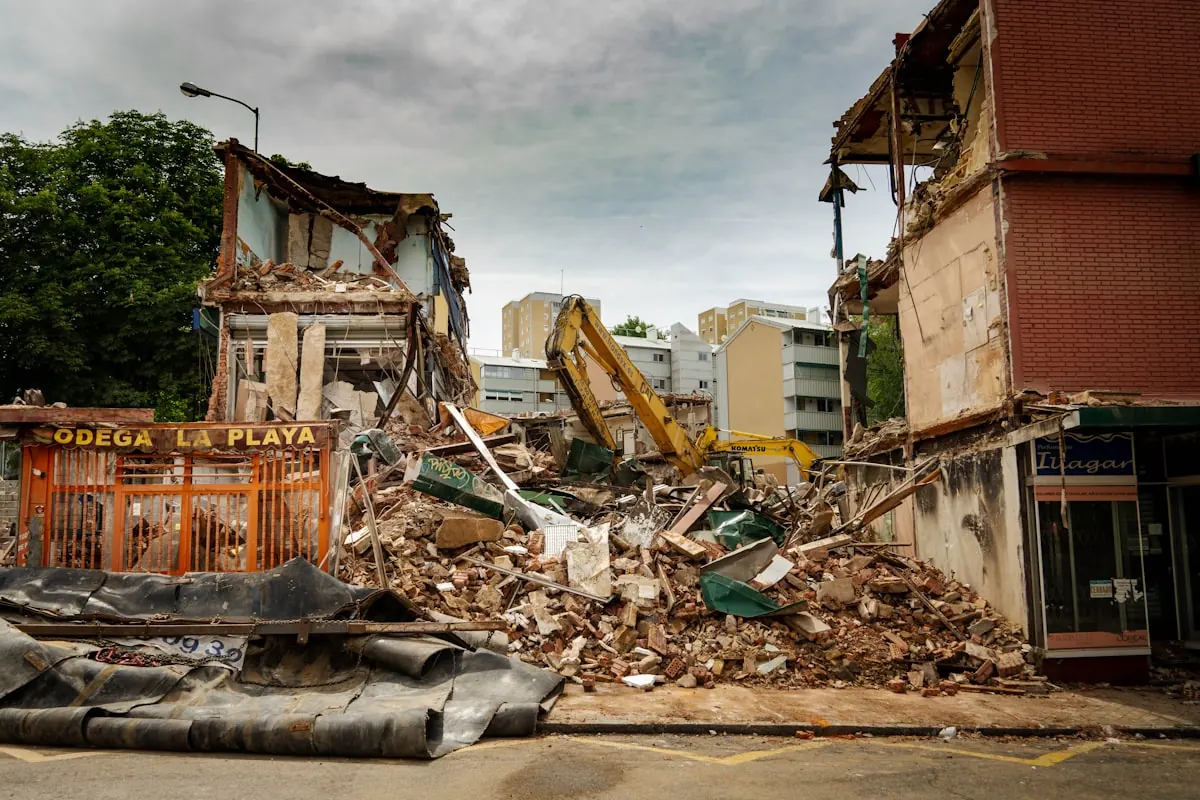
Most property owners assume their standard policy covers ground shaking, but standard homeowners policies explicitly exclude damage caused by seismic activity. Without dedicated earthquake insurance, structural damage from fault ruptures, ground settlement, or soil liquefaction falls entirely on your shoulders. If a major event strikes your region, your primary home insurance will pay zero dollars toward repairing your foundation or walls.
The exclusion exists because seismic events create simultaneous, widespread claims that can strain an insurer's capital reserves. Unlike localized fires or burglaries, a single tremor can affect tens of thousands of homes across an entire metro area within seconds. Insurers separate this risk into standalone policies or optional endorsements to keep standard home policy premiums manageable for everyone.
Fire damage triggered by a quake presents a rare exception to this general rule. In many states, standard homeowners policies will cover fire damage caused by ruptured gas lines following a tremor, even if shaking damage is excluded. However, establishing where shaking damage ends and fire damage begins often leads to complex claims disputes and prolonged processing times.
Additional living expenses, such as temporary rental costs while your home undergoes reconstruction, are also excluded under standard policies if the underlying damage stems from seismic shaking. Knowing these gaps allows you to evaluate whether adding supplemental policy coverage makes financial sense for your household budget.
How Earthquake Insurance Pricing and Deductibles Work
Understanding how earthquake insurance is structured prevents unpleasant surprises during the claims process. Unlike standard property insurance policies that feature a fixed dollar deductible like $1,000 or $2,500, seismic policies calculate deductibles as a percentage of your total coverage limit. This percentage typically ranges between 5% and 25% depending on your state, region, and risk profile.
If your dwelling is insured for $500,000 and your policy features a 15% deductible, you must absorb $75,000 in structural repairs out of pocket before insurance payouts begin. This structure means the policy functions primarily as catastrophic protection rather than a tool for minor cosmetic repairs. Small drywall cracks or minor chimney touch-ups will usually fall well below your deductible threshold.
Policy coverage is usually divided into three distinct buckets: dwelling, personal property, and loss of use. In many policies, each bucket carries its own separate deductible, though some modern insurers offer combined single deductibles. Dwelling coverage addresses structural elements like foundations, framing, and roofs, while personal property covers furniture, electronics, and clothing.
Annual premiums vary dramatically based on location, construction type, and local soil conditions. A wood-frame home built on solid bedrock in a moderate risk zone might cost a few hundred dollars per year to insure. Conversely, an unreinforced masonry building constructed on soft fill soil near an active fault line can incur thousands of dollars in annual premiums.
Evaluating Your Personal Risk and Fault Proximity
Determining whether you need coverage begins with an accurate assessment of your local geology and structural risk factors. Proximity to active fault zones serves as the primary risk factor, but ground composition plays an equally crucial role. Properties built on uncompacted fill, ancient lakebeds, or high-water-table soils face liquefaction risks that amplify shaking severity. You can inspect recent global activity on our real-time earthquake map to observe active seismic trends in your region.
Building materials and construction age significantly influence structural vulnerability during a major tremor. Wood-frame single-family homes are naturally flexible and generally perform well during ground shaking, whereas unreinforced brick or concrete structures suffer severe brittle failure. Homes constructed before modern seismic building code updates - typically pre-1980 in California or pre-1990 in the Pacific Northwest - often require retrofitting to survive severe shaking.
Retrofitting measures like bolting the house frame to its concrete foundation and reinforcing cripple walls substantially reduce structural collapse risk. Many insurance providers offer premium discounts ranging from 10% to 30% for verified seismic retrofits. Investing in foundation anchor bolts not only protects your physical safety but also reduces long-term insurance costs.
Regional risk extends far beyond California and the West Coast. The New Madrid Seismic Zone in the central United States, the Wasatch Front in Utah, and parts of South Carolina all possess historic records of powerful tremors. Homeowners in these regions frequently underestimate their exposure due to long intervals between major historical events.
Renters, Condos, and Mobile Homes: What You Need
Tenants and condominium owners often mistakenly assume they have no need for seismic protection because they do not own the main building structure. For renters, personal property policies can be purchased for a fraction of full homeowner rates, often costing under $100 per year. Replacing damaged electronics, furniture, and personal items after a major event can prove financially exhausting without coverage.
Condominium owners face a complex situation involving shared building structures and HOA master policies. While your HOA master policy may cover the building frame and common areas, it often carries a high master deductible. If a major quake damages the complex, the HOA board may issue a loss assessment to every unit owner to cover that massive deductible.
Specialized condo loss assessment coverage helps protect individual unit owners against these unexpected multi-thousand-dollar HOA bills. Standard condo unit policies cover interior walls, kitchen fixtures, and personal belongings, but require explicit add-ons for seismic events. Reviewing your HOA bylaws alongside your insurance agent helps identify where association liability ends and personal liability begins.
Mobile home and manufactured home owners must also take extra precautions. These structures can slide off their pier foundations during moderate shaking if they lack adequate tie-down anchoring systems. Adding specialized mobile home earthquake policies ensures coverage for both re-leveling expenses and structural repair costs.
How to Decide If Earthquake Coverage Is Right for You
Deciding whether to purchase coverage comes down to weighing potential financial loss against your household risk tolerance and budget. If a major structural failure would force you into financial insolvency or foreclosure, carrying a high-deductible policy acts as a vital safety net. You can review broader safety strategies in our complete earthquake preparedness guide to strengthen overall resilience.
Start by requesting quote estimates from your current home insurer or dedicated state authorities, such as the California Earthquake Authority for California residents. Compare different deductible percentages to find a balance between affordable annual premiums and manageable out-of-pocket costs during a disaster. Ensure that the loss-of-use coverage limit covers at least 12 to 24 months of local rental housing costs.
If policy costs prove prohibitive in high-risk zones, focus your resources on physical mitigation. Retrofitting your home, securing water heaters, strapping heavy furniture, and maintaining an emergency reserve fund provide substantial protection even if formal insurance is out of reach. Physical retrofitting reduces structural collapse risk, keeping your family safe while preserving your equity.
Reevaluate your insurance decision every few years or whenever you undertake home renovations. Updating structural bracing or paying down your mortgage principal alters your financial risk profile over time. Staying informed about geological risk and policy options allows you to protect your family and financial future with confidence.
Related Reading
FAQ
Frequently Asked Questions
Does normal homeowners insurance cover earthquake damage?
No, standard homeowners and renters insurance policies almost always exclude damage caused by earthquakes, soil liquefaction, and ground settling. You must purchase a separate policy or add an endorsement to get seismic coverage.
How are earthquake insurance deductibles calculated?
Unlike standard dollar-based deductibles, earthquake policy deductibles are calculated as a percentage of your total insured dwelling limit, typically between 5% and 25%. On a home insured for $400,000 with a 10% deductible, you pay the first $40,000 of repairs.
Is earthquake insurance worth the money?
It depends on your fault proximity, home construction, soil type, and equity position. If major structural damage would destroy your financial stability, carrying catastrophic policy protection is generally recommended.
Does earthquake insurance cover personal property?
Yes, most earthquake policies include personal property coverage for furniture, appliances, and clothing, though personal items usually carry their own separate deductible percentage.
Can retrofitting my home lower my earthquake insurance premium?
Yes, installing foundation anchor bolts, cripple wall bracing, and seismic shutoff valves can earn premium discounts between 10% and 30% from participating insurance carriers.
Track Seismic Risk Near You in Real Time
Monitor global tremors and check fault line activity around your home using the Earthquake Globe app.